
A trader requests a withdrawal on Friday evening. By Monday morning, the request still shows as pending, and no money has reached the bank account. Is the broker checking the transaction, or has the payment already been sent?
Knowing how withdrawals work makes situations like this easier to handle.
When a withdrawal remains pending, traders need to know which part of the process is holding it up. Some requests require additional identity checks, while others have already moved to the banking stage. AIMS, a forex and CFD broker, addresses payment verification and withdrawal requirements in its published trading terms. Its 24/5 support service also gives traders a direct channel for account-related questions.
Understanding where a request stands helps traders identify the next step and avoid unnecessary confusion when funds take longer to arrive.
From Withdrawal Request to Bank Account
A withdrawal passes through several stages. The broker checks the request, confirms account information and releases the funds through the selected payment channel. The receiving institution then completes its part of the transfer.
A request marked as processed by the broker does not necessarily mean that the money has reached the trader’s bank account.
The following table shows what happens at each stage and what traders can check.
| Withdrawal stage | What happens | What traders should check |
|---|---|---|
| Request submission | The trader selects an amount and payment destination | Available balance, payment method and withdrawal limits |
| Account verification | The broker confirms identity and payment ownership | Required documents, registered details and outstanding verification requests |
| Broker processing | The withdrawal is checked and released through the relevant payment channel | Request status, processing conditions and transaction reference |
| Payment settlement | The bank, card issuer or e-wallet provider completes the transfer | Receiving account, currency conversion and any third-party charges |
The stages also explain why depositing money and withdrawing it can take different amounts of time. Payment networks, verification requirements and banking schedules all influence the overall experience.
A Friday Withdrawal Delayed by KYC Checks
Consider a hypothetical example involving Leon, a forex trader requesting a $1,200 withdrawal late on Friday.
His account has enough available funds, but the broker needs updated proof of address. The document previously submitted is no longer valid for verification.
Leon uploads a recent bank statement on Monday. The broker checks the information against his registered account details before releasing the payment.
Even after approval, the bank still needs to complete the transfer.
The delay comes from two separate stages: account verification and payment settlement.
For traders facing a similar situation, the first useful question is whether the withdrawal is still awaiting approval or has already been sent to the payment provider.
AIMS’ account documentation requirements include identity verification and relevant banking information, making accurate records important when submitting withdrawal requests.
Payment Methods and Withdrawal Conditions at AIMS
AIMS provides several ways to fund trading accounts, including bank transfers, cards and e-wallets, and does not charge deposit fees.
Each payment method involves its own processing network. Bank transfers move through financial institutions, while card and e-wallet transactions follow the relevant provider’s procedures.
Withdrawal destination rules are a separate consideration. Clients may also need to provide additional identification or source-of-funds documents.
For example, a trader who originally deposited through a bank account should check whether the withdrawal must return to that account. Changing the receiving destination can require further verification.
These procedures help protect account ownership and support anti-money-laundering controls.
The same principles are relevant when examining withdrawal policies across the forex industry.
Working Out the Actual Cost of a Withdrawal
A withdrawal fee is only one part of the cost of transferring money.
International payments can involve intermediary banks, receiving-bank charges and currency conversion. The amounts vary by provider and payment route.
Consider an illustrative $1,000 international bank transfer. If the intermediary and receiving banks charge a combined $20, the recipient receives $980 before any currency conversion.
If the destination account uses another currency, the exchange rate can change the final amount further.
AIMS confirms that it does not charge deposit fees. Traders arranging withdrawals should check the charges attached to their selected payment method and the banking institutions involved.
The practical figure is the net amount arriving in the receiving account after the applicable charges have been deducted.
Account Verification and Payment Security
Most withdrawal problems are easier to resolve when the trader’s identity documents, banking information and transaction records are complete.
AIMS requires identity and address documentation during registration. Also allow additional verification where necessary for compliance purposes.
For an account holder, this means keeping registered personal details consistent with payment records and responding promptly to legitimate document requests.
Payment security extends beyond document checks.
Customers should use verified communication channels when checking withdrawal status or submitting sensitive information.
Getting a Clear Answer When Funds Are Pending
When a withdrawal remains pending, knowing which institution currently holds responsibility for the transfer helps narrow down the issue.
If the request is still with the broker, ask whether additional verification is required and confirm the recorded payment details.
If the broker has released the money, request the payment reference. The receiving bank or payment provider can use that information to trace the transfer.
Keep the withdrawal amount, submission date, transaction ID and relevant correspondence together. These records are useful if the issue requires further investigation.
For AIMS clients, the official support channels provide a way to check account documentation and the status of payment-related inquiries.
Before Submitting a Withdrawal
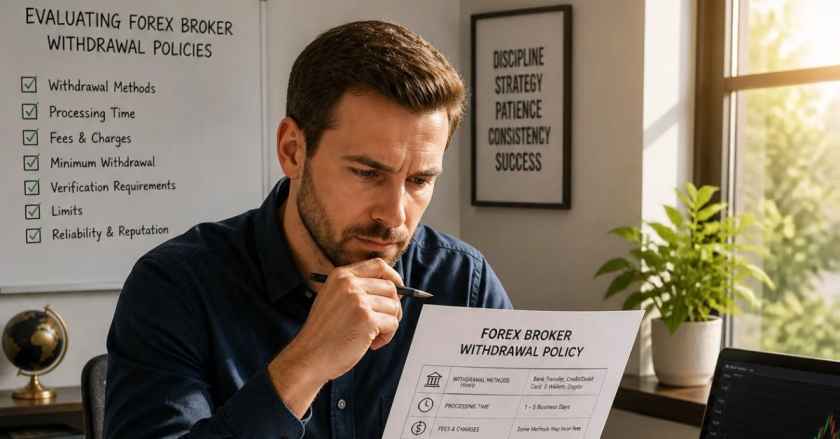
A clear withdrawal policy helps traders understand where their money goes, what checks are required and which charges may apply.
AIMS publishes information about its funding methods, account verification requirements and customer support. Before submitting a request, traders should confirm their chosen payment route, available balance, receiving-account details and applicable charges.
A few minutes spent checking those details can prevent unnecessary complications when moving funds out of a trading account.